A Zen saying warns: “The person who reaches the goal has missed everything else.” That idea captures what often happens when revenue growth becomes the center of a company’s strategy, and even more so when the focus shifts almost entirely to EBITDA growth.
EBITDA captures only part of operating performance and can be useful for comparing or valuing companies. It still tells an incomplete story, because interest, taxes, depreciation, and the capital required to maintain assets eventually catch up with the business. We sometimes jokingly refer to creditors and tax authorities as the “priority shareholders” because they get paid before the actual shareholders when the value created is distributed.
Revenue and EBITDA reveal even less about a company’s robustness. They say little about product and service quality, customer loyalty, employee engagement, innovation capacity, the strength of the business model, or the company’s ability to withstand future shocks.
Yet our economic ecosystem places enormous emphasis on growth. Business schools teach its mechanics, financial institutions and private equity firms finance its acceleration, government programs support it, and the media regularly celebrate the companies growing the fastest.
This obsession is a textbook example of Goodhart’s Law: “When a measure becomes a target, it ceases to be a good measure.” Once revenue or EBITDA becomes the goal, decisions gradually start optimizing the metric instead of strengthening the company.
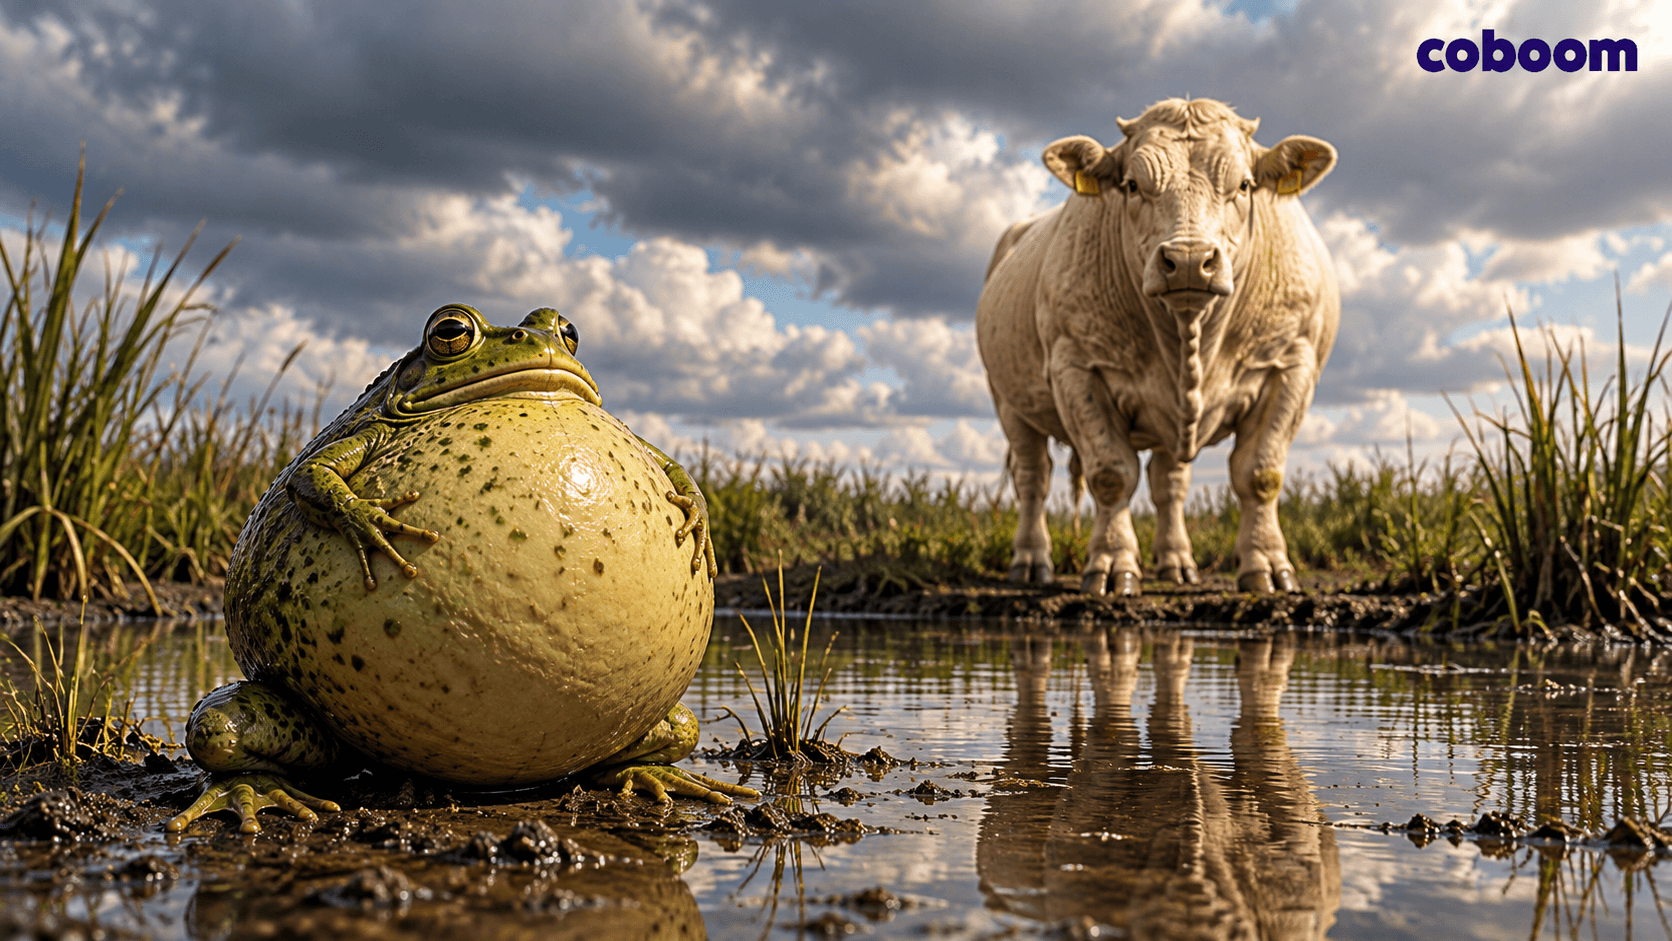
We then see businesses cut prices to buy market share, take on difficult or unprofitable customers, spread themselves across too many markets, and multiply products and services. Like the frog in La Fontaine’s fable that wanted to grow as large as the ox, they expand while complexity, debt, working capital requirements, and employee fatigue sometimes grow even faster.
Revenue rises, EBITDA improves, while net income, cash flow, and financial resilience may tell a much less impressive story. Growth then becomes a source of fragility rather than a sign of strength.
A robust company follows a different logic. It deliberately chooses the markets, customers, products, and capabilities that strengthen its long-term viability, then accepts growth when that growth genuinely improves its position rather than simply making the numbers look better.
In the 21st century, that distinction is becoming strategic. Long-term economic, social, ecological, technological, energy, and geopolitical trends are already reshaping the conditions in which companies operate, and their effects will continue to intensify through 2040.
Real performance now means building a company that can endure, adapt, and continue creating value through disruption. Growth can support that path, but robustness must guide it.